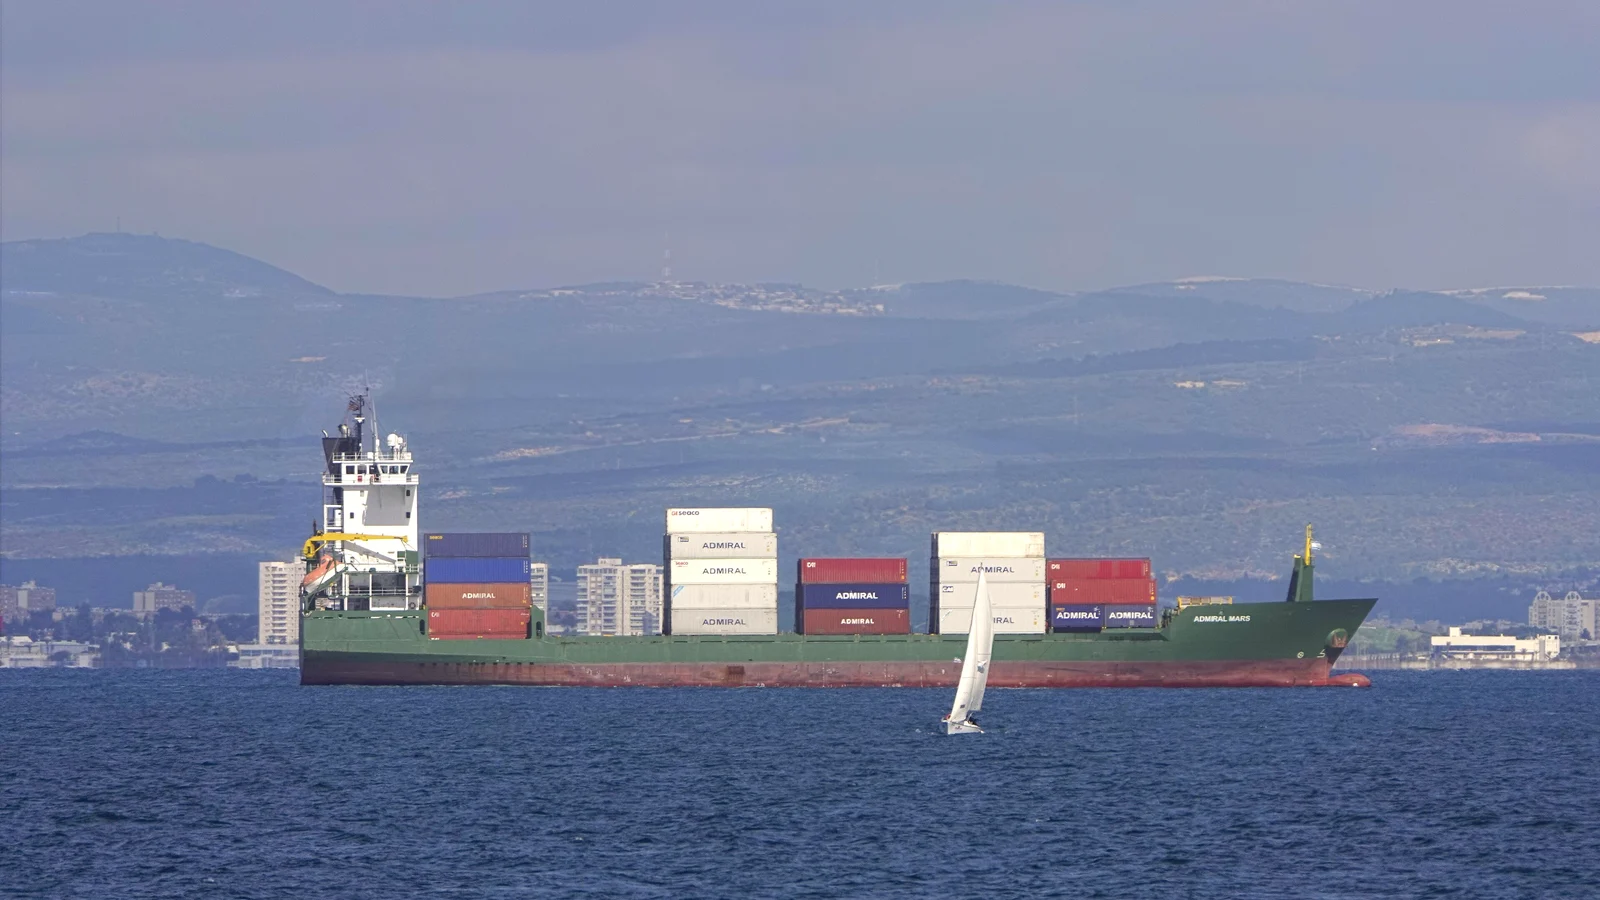
Container schedule reliability fell to 27% in September, the fourth monthly drop in a row, according to Xeneta’s schedule reliability scorecard. Far East to Europe managed 4% on time, with 9.9 days of average delay. Between 9 July and 8 October, Shanghai to Genoa on Drewry’s World Container Index fell from $6,463 to $3,696 per 40ft, as quoted in Sogese’s October update, reported by Hellenic Shipping News. My reading: anyone who books on the rate drop alone is committing to a date that the on-time figures make unlikely.
I would not plan around the 27%. Shipping schedule reliability varies by lane, and the global figure blends Far East to Europe (4%) with Far East to North America (20%, delay up 0.8 days to 6.9) and Europe to North America (49%, 1.9 days of delay, the lowest of any trade). Xeneta sees little prospect of a firm floor in October.
What counts as late
Xeneta measures container schedule reliability at the destination port, against the schedule the carrier originally published. Forecast ETAs the carrier sends later are not used. A call is on time within one calendar day either side, and an early arrival scores null, so it never offsets a late one. If a service calls ten ports and six calls are on time, the service scores 60%. Xeneta’s methodology page is short, and worth reading before you quote the number to a customer.
Eight days is a floor
Sogese, an Italian container logistics provider, tells importers to add at least eight days to Far East to Italy arrival dates until Xeneta’s September scorecard shows Far East to Europe above 20% on time. It wrote that when August stood at 6% and 8.2 days of delay. The September scorecard has since landed at 4% and 9.9 days, so Sogese’s own test is already missed. The 9.9 is a whole-trade average and the eight is a minimum for one corridor, so the two don’t compare directly.
Italy can sit at the back of the rotation. On Maersk’s AE11, moved to Suez from 19 September, the calls run Shanghai, Yantian, Tanjung Pelepas, Suez, Tangier, Valencia, Barcelona, La Spezia, Genoa and Vado Ligure. Sogese notes that Italian importers are the last discharge, so delay picked up earlier reaches them last. For a Genoa box on a rotation like that, I would pull the service’s own arrival history before trusting any buffer, including Sogese’s.
Space is tightening on the other side of the holiday. Sogese says cargo held back by Golden Week ships in weeks 42 and 43 and lands in Europe between mid-November and early December, and that a late booking risks rolling to week 44. Week 42 began on 12 October, so that window is already open.
The saving has a second bill
By Sogese’s sums, a shipper moving 100 FEU a month from Shanghai to Genoa pays about $277,000 less per month than at the 9 July rate. The index excludes destination terminal handling, so demurrage, detention, terminal charges and inland haulage can keep landed cost from falling with it. My guess is that the saving erodes when a vessel arrives nine days late and the free time and the truck slot were booked against the original date. No source I read puts a figure on that.
Sogese also advises short rate commitments, and no Mediterranean rates fixed beyond three months until weekly Suez transits stop rising. Its CEO Andrea Monti puts the rule for importers this way: “Book on the rate and date your stock on the delay.” Sogese wrote for Europe. I would hesitate to copy the short-commitment advice across the Pacific, where Xeneta’s China to US West Coast spot average reached $7,717 per FEU in early October, over four times September 2025, and long-term rates were $3,649 on 1 October, up 26% in a month. Xeneta says contracts are repricing upward, so renewals are likely to cost more (scorecard).
Blanks and Suez can both move the date again
Drewry’s tracker expects 34 blank sailings out of 713 planned across the main East-West trades from week 42 to week 46, a 5% cancellation rate, half of it on Asia to North Europe and the Mediterranean. Xeneta puts announced October blanks at no less than 17% of planned capacity on Far East to Europe and 13% on Far East to North America. The denominators differ, so don’t set 5% beside 17%. Xeneta adds that the announced share is still below October 2025, which could mean carriers are keeping capacity in rotation to work off the typhoon backlog, or that more cancellations are coming. Planned Far East to Europe capacity for October is the highest of any month in a 22-month window, which leaves a trade at 4% on time with even less slack to offset delays through voided sailings. Xeneta advises more lead time on October bookings and asking each carrier which services are protected from cuts.
On Suez, Lloyd’s List Intelligence puts September containership traffic through the canal at 2.19m TEU, up 40% on August and far under the 5.9m TEU of September 2023. The same brief logs a Chinese-operated containership fired upon off Yemen on 7 October, all crew safe. Sogese reports that on 14 September Maersk and Hapag-Lloyd moved four Gemini services back to Suez and said further changes depend on stability in the Red Sea area. It says each conversion takes one to two weeks off the voyage and helps planning only where the receiving terminal is ready for earlier arrivals, and that every plan needs a Cape-routing contingency.
What I would put in the 2027 tender
Every carrier Xeneta tracks posted its highest average delay of the past 12 months in September. The gap between best and worst narrowed to 43 points. Yang Ming’s 4% pulled the floor down and Maersk’s drop from 51% to 47% pulled the ceiling down, which Xeneta reads as leaders falling with no catch-up from the laggards. The Gemini network of Maersk and Hapag-Lloyd dropped from 70% on time in June to 40% in September, and partial data for the week of 5 October reads 28% (all from the Xeneta scorecard).
Xeneta says reliability, port rotations and unscheduled calls belong in carrier accountability talks before 2027 tenders. I would add one ask of my own: the on-time figure for the specific service on each lane you ship, because a carrier-wide percentage hides the weak rotation. We made the case for reading lanes, and the p50 to p90 spread, in which carrier sails on time. On the Navo side, SchedulesMCP covers 72,000+ sailings on 5,000+ lanes with reliability scoring, and FreightRatesMCP gives daily ocean spot rates with trend analysis. Both sit on the same events as the rest of the suite, which covers 229 carriers for container tracking, with tracking events 0 to 5 minutes fresh, cross-checked across 2 to 3 sources. You can work in the dashboard, call the REST API, or hand the question to an agent over MCP.
Frequently asked questions
The ETA on my booking says the 20th, but I keep reading that vessels are mostly late. How much should I trust the date?
Treat it as a starting point. Xeneta scores carriers against the schedule they first published, and only 27% of arrivals landed within a day of it in September. The service's own recent arrival history tells you more about your buffer than the date on the confirmation.
Does 27% on time mean 73% of my containers will be late?
Xeneta's figure is a share of vessel arrivals at the destination port, so it won't map one to one onto your boxes. How late matters too. Average delay was 6.0 days, and Xeneta says buffer days in contracts and inventory plans are being consumed at an alarming rate.
Should I wait for rates to fall further before I book?
Sogese's base case is a further fall through the fourth quarter. In its scenario where Suez capacity outpaces demand, Shanghai to Rotterdam reaches $2,763 and Genoa about $3,100. It reads blank sailings at or below seven a week in weeks 43 and 44 as pointing to further declines. Sogese also cites Xeneta chief analyst Peter Sand saying on 8 October "we are not at the floor yet", in the rates part of its report. My take: let the cargo decide. Boxes that must land by early December are already in the booking window Sogese describes, while cargo with slack can watch the blank-sailing count.
I pay extra for a premium carrier. What do I get to ask for?
Xeneta says shippers should hold carriers that charge a premium for reliability to account going into 2027 tenders. Ask for the on-time record of the service you are buying, its port rotation, and which services are protected from capacity cuts.