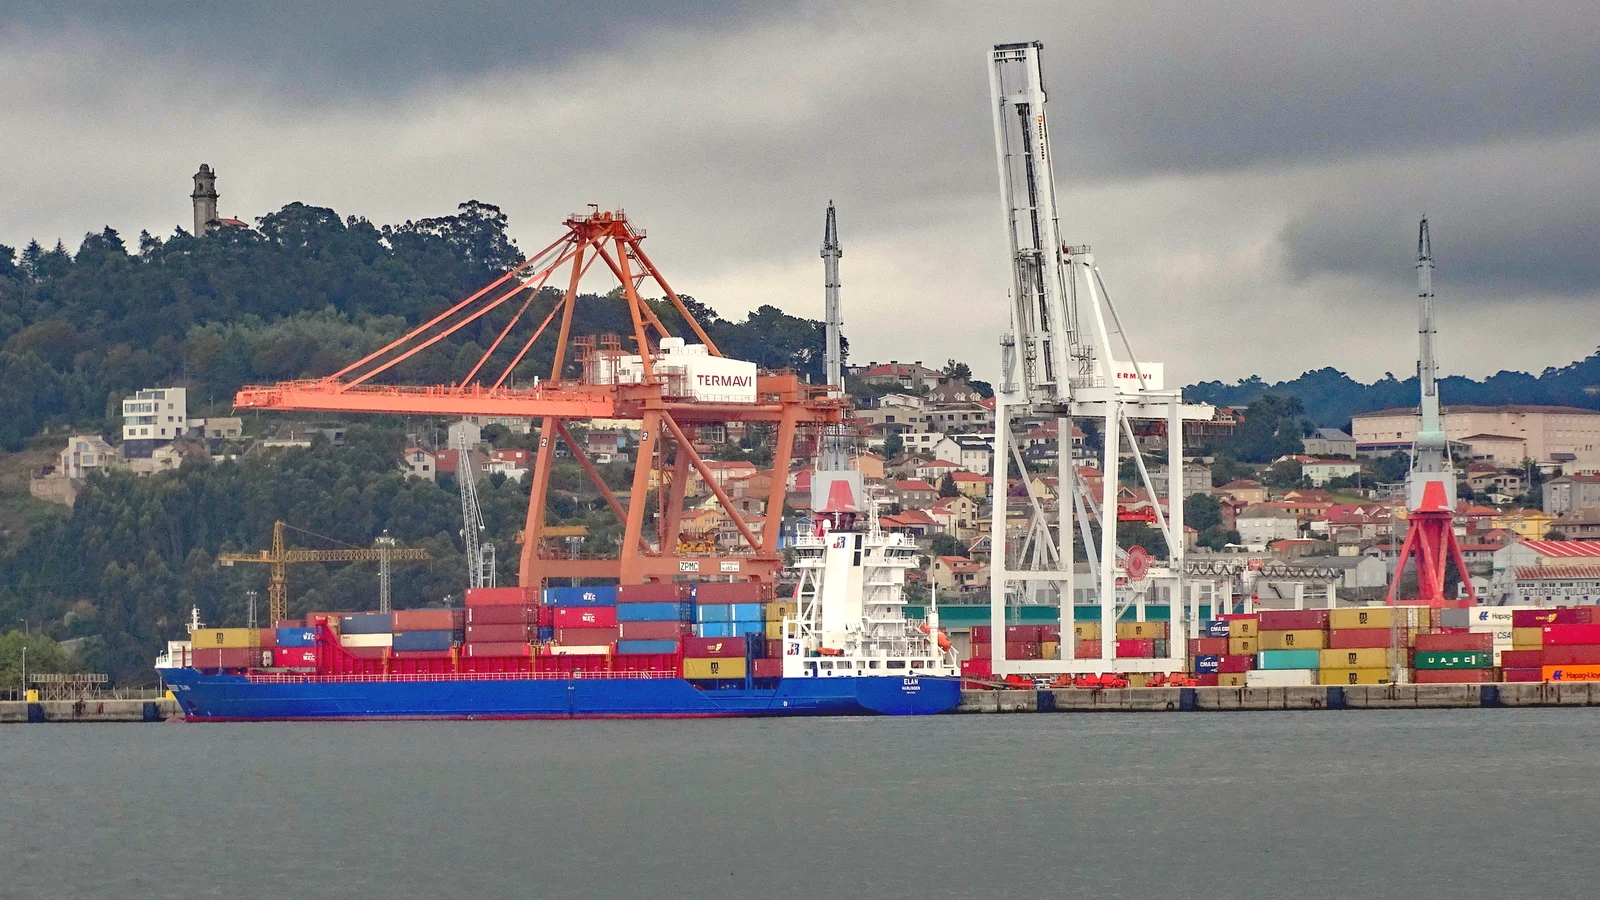
MSC published its Asia Europe FAK rates on 28 September with an expiry date attached. In its advisory the new rates start on Monday 19 October and run “until further notice but not beyond 31 October”, which leaves the tariff less than two weeks. Whether anyone books at that level is a separate question.
A European forwarder quoted by The Loadstar on 16 October says the increases planned for the second half of October had been pushed back to the 19th, and that downward revisions had arrived that morning, “almost back to the levels we saw in the first half of October”. Demand was still flat, he added. A second forwarder said an end date on a FAK usually means carriers expect rates to soften, because in the forwarder’s experience carriers do not normally raise prices before the period expires. Two forwarders are a small sample.
What sits inside each carrier’s number
FAK stands for freight all kinds: one freight rate for various kinds of goods shipped together. MSC’s notice excludes IMO-class and high-value goods.
Hapag-Lloyd’s customer notice, reproduced by Container News, puts North Europe at $4,200 for sailings with a tariffing date on or after 19 October. Marine Fuel Recovery is in that rate, and the rate stays subject to Hapag-Lloyd’s tariff conditions and other applicable surcharges. Hapag-Lloyd’s own page adds terminal handling and security-related charges to that list. MSC’s North Europe rate is $4,500 per 40ft high cube and is built differently: its global fuel surcharge and emission control charge are inside, while carbon surcharges sit under “subject to”. CMA CGM is at $4,600 to North Europe, according to The Loadstar, and the report does not say what that figure includes.
Why $3,522 and $4,500 are not the same kind of number
On 15 October Drewry’s World Container Index had Shanghai to Rotterdam at $3,522 per 40ft, up 6% on the week. After 13 consecutive weeks of decline, spot rates on the Asia-Europe route turned up, and Shanghai to Genoa rose 7% to $3,945. MSC’s filing sits $978 above the Rotterdam reading.
Drewry’s methodology builds the index from agreed dry-cargo rates and says outright that rates from quotes, tariffs, estimates, bids or offers are not included, so a published FAK tariff is not in it. Bunker and other surcharges are counted, and terminal handling only where market practice includes it. The two carrier notices both say terminal handling can come on top. MSC’s filing also covers all Far East ports, while the index follows one port pair. How much of the $978 would survive on an invoice cannot be worked out from the published documents. Navo’s FreightRatesMCP publishes an indicative daily spot rate per lane, stamped with the date it moved, an indicative number to anchor on before asking anyone for a quote.
The FAK range Drewry reports for the Asia-Europe route is $4,500 to $4,800 from 19 October, which puts Hapag-Lloyd’s $4,200 below it. Its comment: “successful implementation of these FAKs remains uncertain amid increased capacity”. It expects rates to hold steady next week.
Suez capacity is arriving as the filings start
Linerlytica, quoted by The Loadstar on 6 October, called the Suez return the biggest threat to carriers trying to reverse a three-month slide. ONE had just become the latest major carrier to resume transits, after CMA CGM, Maersk, MSC, Hapag-Lloyd and Cosco/OOCL. The route matters for the bill: MSC’s notice makes a piracy risk surcharge of USD 55 per TEU and a Suez Canal surcharge of USD 36 per TEU subject to services passing via Suez, so two sailings at the same filed rate can invoice differently depending on the rotation. The report adds that Asia-North Europe rates had fallen around 60% since July, as of 6 October. Drewry’s 15 October note counts two blank sailings for the coming week against six this week and reads that as more effective capacity.
Freightos reported Asia to North Europe flat on the week on 13 October and Asia to the Mediterranean up 7% to $3,800 per FEU. Both lanes sat about 70% above last year even after the slide. Freightos also says 2027 contract tendering is starting and recalls that carriers cut capacity and pushed Q4 general rate increases last year to lift the benchmark for long-term talks. None of the sources states a link between the 19 October filings and this year’s tender. Neither the notices nor the index show what a shipper was actually invoiced for a given sailing.
On-time arrivals on the lane fell to 4% in September
Xeneta’s September scorecard, published 12 October, has Far East to Europe at 4% on-time with 9.9 days of average delay across all vessels, the worst month on that trade since September 2021. Jon Charles of WiseTech told The Loadstar that only 9.9% of shipments arrived on time in September and that delays of eight days or more now make up almost half of volume. One figure counts vessel arrivals and the other shipments, and neither source says why 4% and 9.9% differ. Xeneta’s own advice for October is more lead time, and a question to the carrier about which services it is protecting from capacity cuts.
A box that has to land by a date depends on the sailing first. Navo’s SchedulesMCP scores on-time performance per lane from arrivals observed through the tracking layer, and labels thin lanes as early data. The same events sit under FreightRatesMCP, so the lane you priced is the lane you track. The reasoning behind treating reliability as a lane fact is in which carrier sails on time.
For cargo with slack, the forwarders quoted by The Loadstar expect rates to fall again, and the MSC filing lapses on 31 October. Before putting any quote next to $3,522, ask which of terminal handling, fuel and the Suez surcharges it contains. The MSC and Hapag-Lloyd documents list different items outside the base rate of their Asia Europe FAK rates.
Frequently asked questions
Which MSC surcharges are inside the $4,500 and which are added?
MSC's notice puts the global fuel surcharge (USD 253 per TEU for October) and the emission control charge inside the rate. The emission charge is USD 15 per TEU for the main North Europe and Mediterranean destinations and USD 52 per TEU for other Nordic and Baltic ones. Listed as subject to: the carbon limitation surcharge (USD 20 per TEU), the carbon review surcharge (USD 88 per TEU to North Europe, USD 128 to the Mediterranean), and on services via Suez the piracy (USD 55) and Suez (USD 36) surcharges. All of these are per TEU, and the $4,500 is per 40ft high cube. The notice quotes no terminal handling figure and says it and other applicable charges may also apply.
Is the MSC rate the same to the Mediterranean?
Not everywhere. For a 40ft high cube MSC lists $4,500 to West Med and the Adriatic, $4,800 to East Med and $5,000 to the Black Sea. Hapag-Lloyd's own table splits the Mediterranean as well, with West Mediterranean and Adriatic at $4,600 and Egypt, Turkiye and East Mediterranean at $5,100. MSC's rates are base port to base port, so a box to an out-port is subject to the usual TAO or TAD.
How long do the 19 October rates last?
MSC's filing ends on 31 October at the latest, and The Loadstar reports the same end date for CMA CGM. Hapag-Lloyd's notice applies to sailings with a tariffing date on or after 19 October and says only that the rates are valid until further notice.