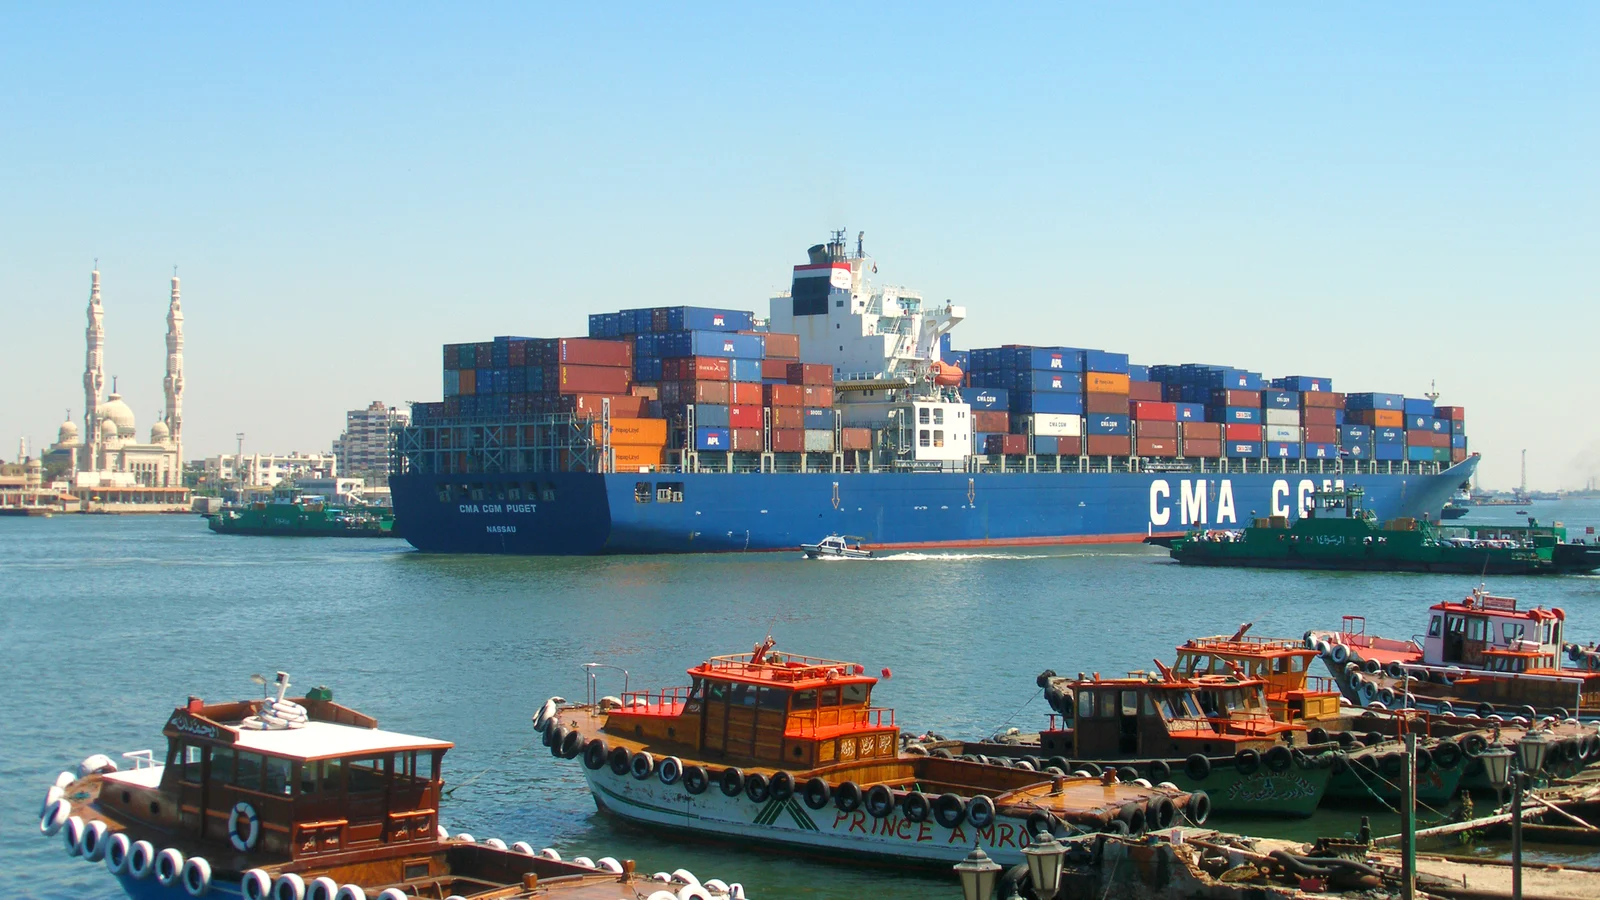
Weekly container capacity scheduled across Bab el-Mandeb reached 448,273 TEU on 5 October, double the level of 27 August, according to Xeneta’s update of 16 October. That is 48% of the 930,679 TEU offered in August 2023, before carriers began routing around the Cape of Good Hope.
Annual contracts for 2027 are being tendered now, and the Red Sea return is already moving container rates.
Scheduled capacity and ships that passed
The Xeneta figure counts services that transit the region or are set to start, in at least one direction. Container News, reporting BIMCO and Clarksons Research data, counts what went through: an average of 753,000 TEU a week in the first two weeks of October against 1.46 million TEU in the same weeks of 2023. The canal carried 36% of the capacity routed through either the canal or the Cape, up from an average of 8% between 2024 and mid-2026 and still short of the 80% seen before the attacks.
Xeneta’s senior analyst Emily Stausbøll says only carriers can explain what changed in their security assessments over the six weeks. BIMCO’s Niels Rasmussen estimates that rerouting added about 10% to demand for container ship capacity, and that this addition “is now reducing quickly”. Congestion slows the effect on capacity: Xeneta expects the released ships to be partly absorbed by congestion in ocean networks “at least for now”, and BIMCO says congestion at Asian ports could delay the full impact on vessel availability.
Asia-Europe rates turned up ahead of the 19 October FAK date
Judah Levine of Freightos, in a weekly update republished by Container News, writes that Asia-Europe spot rates fell from July, and that the post-peak slide in demand mattered more than the growth in Red Sea transits. Xeneta’s 16 October averages have Far East to North Europe at $3,568 per FEU, up 2.5% on the week, and the Mediterranean at $4,165, up 3.2%. Stausbøll says this is likely the balance of supply and demand correcting rates that had fallen far enough.
Drewry’s World Container Index, as of 15 October, put Shanghai to Rotterdam at $3,522 per 40ft, up 6%. The Loadstar lists the FAK levels due on 19 October to North Europe: $4,200 from Hapag-Lloyd, $4,600 from CMA CGM and $4,500 from MSC.
A European forwarder told the paper that downward revisions to those increases had already arrived, almost back to the levels of the first half of October. Another noted that MSC and CMA CGM limited validity to 31 October, which in the forwarder’s experience points to carriers expecting rates to soften.
Drewry’s 8 October commentary, as summarised by CargoLinked, called the faster-than-expected return to Suez the biggest threat to carriers’ efforts to support rates.
US trades hold their level while carriers cancel departures
Far East to US West Coast stood at $8,296 per FEU and to the East Coast at $11,495, both within 0.2% of the previous week. Carriers blanked 58,200 TEU on the West Coast trade and 35,500 TEU on the East Coast trade that week. US spot rates are still up triple-digit percentages on February, before the Hormuz crisis. Carriers would normally add capacity at that level, Stausbøll says, so she reads the blanking as carriers who do not believe the market will hold and are protecting the current level.
A US West Coast forwarder, Freight Right, told The Loadstar that carriers are clearing Golden Week backlogs first and that limited availability “does not necessarily indicate stronger overall demand”.
What the 2027 tender has to assume about Suez
Freightos describes tender season as the point where, a year ago, carriers cut capacity and pushed through Q4 general rate increases to raise the benchmark for long-term talks. Asia-Europe rates above $3,000 per FEU on both lanes are still about 70% higher than a year earlier, and some shippers expect rates to ease in 2027 on newbuild deliveries and further Red Sea transits, so they hesitate to lock in annual rates at current levels.
Xeneta expects the Red Sea return to be one of the drivers of the 2027 market. Drewry’s base case, reported by The Loadstar on 12 October, has Suez transits reaching 80% of the pre-diversion level by February 2027, a forecast of transit levels that is not necessarily the same measure as BIMCO’s 80% pre-attack share of capacity. The same piece quotes Drewry’s slot cost comparison for two services on 24,000 TEU ships: a Suez saving of about $1 million per round voyage, or $43 per slot, which it calls marginal. MSC extended its piracy risk and Suez Canal surcharges through October at $91 per TEU, $55 and $36 respectively.
A 2027 contract needs a stated Suez assumption. Navo’s service-by-service view of the Suez reopening and the Cape reroute transit-day math show what each routing does to the schedule. Ask each carrier which strings in its offer are named Suez services and which go through the canal ad hoc, and whether the Suez and piracy surcharges continue past October.
Antonis Rigalos of the shipper group ShiftX told an Asia-Europe webinar that some insurers have no Suez cover and must be applied to for it, so cover has to be arranged at short notice when a carrier switches a string from the Cape. He added that BCO members report the extra insurance cost has not yet been onerous.